Most payment teams implement dynamic routing and assume the optimization work is done. It isn't. Dynamic routing and smart routing solve fundamentally different problems; and treating them as interchangeable leaves approval rate gains on the table.
This guide explains how each approach works, when each one is the right call, and why the most effective payment stacks use both.
What Is Payment Routing?
Payment routing determines the path a transaction takes from checkout to approval. A routing engine evaluates available processors, card networks, issuing banks, and transaction context — then selects the option most likely to result in a successful authorization, all in milliseconds.
The variables a routing engine works with typically include:
- Card type: credit, debit, or prepaid
- Transaction amount and currency
- Customer location and device
- Card network and issuing bank behavior
- Risk signals and historical approval patterns
Without routing intelligence, every transaction takes the same fixed path, regardless of whether that path is performing well or not. That's the gap routing solves.
The Three Routing Approaches
Static Routing
Static routing follows fixed rules. Every transaction goes to the same processor, in the same order, every time. Easy to configure — but fragile. When a processor underperforms or goes down, there's no fallback. Declines stack up until someone manually steps in.
Dynamic Payment Routing
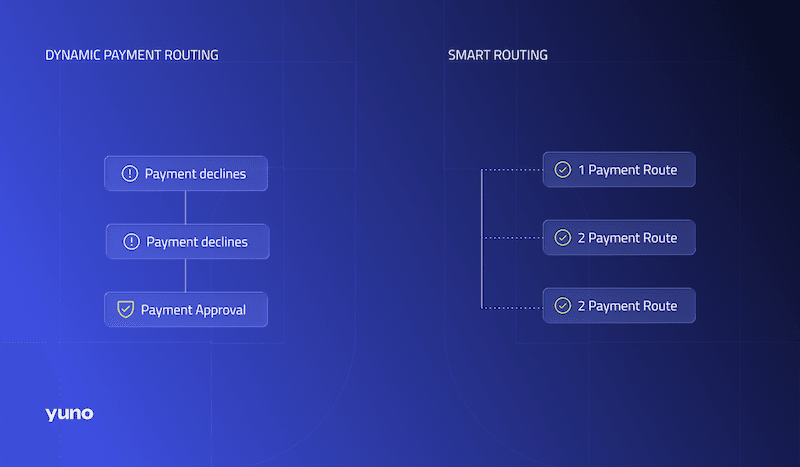
Dynamic routing is reactive. It monitors live signals, uptime, latency, real-time approval rates, and reroutes traffic automatically when conditions change. If a processor slows down or drops off, transactions shift to the next available option without manual intervention.
It's the difference between catching a decline wave early and discovering it hours later in a dashboard.
Smart Routing
Smart routing is predictive. Instead of waiting for a problem to occur, it uses historical data, BIN-level trends, card network behavior, issuing bank preferences, past approval patterns, to select the best route before the transaction is submitted.
The result: fewer false declines, better authorization rates, and less unnecessary friction for legitimate customers.
Dynamic vs. Smart Routing: Side-by-Side
Dynamic Payment Routing Smart Routing Core approach Reactive
Responds to live signals as conditions change Predictive
Selects the best route before problems occur Data used Uptime, latency, live success rates Historical outcomes, issuer behavior, BIN data Logic type Rule-based — high control, manual configuration Model-driven — automated, self-improving Primary goal Reduce declines during outages or disruptions Improve approval rates proactively at scale Best for Multi-region environments with variable performance High-volume merchants optimizing for conversion Typical trigger Processor outage or latency spike Card type, issuer pattern, or risk profile
When to Use Each
Choose dynamic routing when:
- You operate across regions with inconsistent processor performance
- Your stack includes providers prone to outages or latency spikes
- You need automatic failover without touching routing rules manually
- Uptime and reliability are the primary concern
Choose smart routing when:
- You process high volumes where small approval rate gains compound fast
- False declines are costing you conversions
- You want routing to improve automatically over time without manual tuning
- You're optimizing for conversion, not just availability
In practice, the strongest payment stacks don't choose. Dynamic routing handles real-time disruptions. Smart routing handles proactive optimization. Each does what the other can't.
How Routing Affects Approval Rates
Every declined transaction carries a cost beyond the lost sale: retry overhead, support load, churn risk, and eroded lifetime value. Most of these costs never get traced back to routing.
Dynamic routing eliminates declines caused by infrastructure failures. Smart routing eliminates declines caused by suboptimal path selection. Together, they address the two most common sources of preventable payment failure.
For high-volume merchants, a one or two percentage point improvement in authorization rates translates directly to material revenue recovery; without changing the product, the price, or the checkout experience.
How Yuno Approaches Routing
Yuno's payment orchestration platform gives teams access to both dynamic and smart routing through a single integration. Routing rules can be configured without code, provider performance is monitored in real time, and intelligent fallbacks recover failed transactions automatically.
- Real-time dynamic routing with automatic failover
- Smart routing powered by historical data and issuer-level intelligence
- No-code rule configuration for fast iteration
- Centralized analytics across all processors and payment methods
- Full support for cross-border and high-risk payment flows
The Bottom Line
Dynamic routing and smart routing aren't competing strategies. They operate at different layers of your payment stack.
Dynamic routing keeps transactions flowing when conditions change unexpectedly. Smart routing ensures those transactions are already taking the most effective path. Used together, they turn payment infrastructure from a cost center into a measurable growth lever.
The question isn't which one to choose. It's whether your current infrastructure supports both.